Case · 01 · Mobile App · Fintech

A credit simulator for small businesses.

I analysed the credit applications to understand why they were not being completed, and drove the redesign that transformed that process — adding direct value to the credit origination platform.

View the presentation
Client
Fintech LATAM
Role
Lead UX/UI Designer
Year
2024 — 2025
Deliverables
App, design system, research

The starting point

Six of every ten people abandoned the credit application before seeing an offer.

MetricBeforeAfter
Drop-off in the simulation flow 60% −72% Time to accept the credit 7+ days 1 day Completed applications Baseline 2.5× Reported score Not measured 4.1/5

01 · Overview

An app that helps small businesses understand their credit before signing anything.

A Latin American fintech wanted to open access to fair financing for small and medium businesses — but the flows they had were full of jargon, hidden costs, and forms that felt like obstacles.

I joined the rebuild of an internal-client app meant to give users clarity, structure, and a better understanding of the loan offer and origination process.

AAAWgmp1bWIAAAAeanVtZGMycGEAEQAQgAAAqgA4m3EDYzJwYQAAABZcanVtYgAAAEdqdW1kYzJtYQARABCAAACqADibcQN1cm46YzJwYTo4YzIxOGI3OS00YTdjLTRiNTAtYTczYy1kZTllYTQ5OTkzZGIAAAADl2p1bWIAAAApanVtZGMyYXMAEQAQgAAAqgA4m3EDYzJwYS5hc3NlcnRpb25zAAAAALxqdW1iAAAARGp1bWRjYm9yABEAEIAAAKoAOJtxE2MycGEuaW5ncmVkaWVudC52MwAAAAAYYzJzaFHw/Nw805ezhUS/h3eBWv8AAABwY2JvcqNpZGM6Zm9ybWF0bWltYWdlL3N2Zyt4bWxqaW5zdGFuY2VJRHgseG1wOmlpZDo0OTRhYTk1OS03OWFkLTRlZTYtYTQyMC01ZmJiYWUzNjM2ZjFscmVsYXRpb25zaGlwaHBhcmVudE9mAAAB4mp1bWIAAABBanVtZGNib3IAEQAQgAAAqgA4m3ETYzJwYS5hY3Rpb25zLnYyAAAAABhjMnNoyGwgIpiu/akfqNtBLnxSEwAAAZljYm9yomdhY3Rpb25zgqJmYWN0aW9ua2MycGEub3BlbmVkanBhcmFtZXRlcnOha2luZ3JlZGllbnRzgaJjdXJseC1zZWxmI2p1bWJmPWMycGEuYXNzZXJ0aW9ucy9jMnBhLmluZ3JlZGllbnQudjNkaGFzaFggb0wRRsQ9xcPvULIofnI1y72SGQntGBT9qBe/4D7q6O2kZmFjdGlvbngdY29tLmFudGhyb3BpYy5jbGF1ZGUucHJvdmlkZWRqcGFyYW1ldGVyc6F4H2NvbS5hbnRocm9waWMub3JpZ2luLWNvbmZpZGVuY2VndW5rbm93bmtkZXNjcmlwdGlvbnhmQ2xhdWRlIHByb3ZpZGVkIHRoaXMgZmlsZSBhdCB0aGUgcmVxdWVzdCBvZiBhIHVzZXIgYW5kIG1heSBoYXZlIGNyZWF0ZWQgb3IgbW9kaWZpZWQgdGhlIGZpbGUgY29udGVudHMubXNvZnR3YXJlQWdlbnShZG5hbWVmQ2xhdWRlcmFsbEFjdGlvbnNJbmNsdWRlZPUAAADIanVtYgAAAEBqdW1kY2JvcgARABCAAACqADibcRNjMnBhLmhhc2guZGF0YQAAAAAYYzJzaOyWfuijsBXqe6fck2UNyuQAAACAY2JvcqVjYWxnZnNoYTI1NmNwYWRNAAAAAAAAAAAAAAAAAGRoYXNoWCBItvOb5cSPySd+4eq0TyYzrZKY2L6eNWT2Mked04l+K2RuYW1lbmp1bWJmIG1hbmlmZXN0amV4Y2x1c2lvbnOBomVzdGFydBj7Zmxlbmd0aBkeBAAAAj5qdW1iAAAAJ2p1bWRjMmNsABEAEIAAAKoAOJtxA2MycGEuY2xhaW0udjIAAAACD2Nib3KlY2FsZ2ZzaGEyNTZpc2lnbmF0dXJleE1zZWxmI2p1bWJmPS9jMnBhL3VybjpjMnBhOjhjMjE4Yjc5LTRhN2MtNGI1MC1hNzNjLWRlOWVhNDk5OTNkYi9jMnBhLnNpZ25hdHVyZWppbnN0YW5jZUlEeCx4bXA6aWlkOjMzMGM2NTBmLWMzMTQtNDUyYi1hMzM2LWQ0MDFmNGExNDdlYXJjcmVhdGVkX2Fzc2VydGlvbnODomN1cmx4LXNlbGYjanVtYmY9YzJwYS5hc3NlcnRpb25zL2MycGEuaW5ncmVkaWVudC52M2RoYXNoWCBvTBFGxD3Fw+9Qsih+cjXLvZIZCe0YFP2oF7/gPuro7aJjdXJseCpzZWxmI2p1bWJmPWMycGEuYXNzZXJ0aW9ucy9jMnBhLmFjdGlvbnMudjJkaGFzaFgg3DILqSuyU2ZQ0byShgWK+wOQSGNMP9OdOjpSoltn97miY3VybHgpc2VsZiNqdW1iZj1jMnBhLmFzc2VydGlvbnMvYzJwYS5oYXNoLmRhdGFkaGFzaFggishftFY+FIecW0r9hsVcg2bAPyqBn2y1N5c7rq4d3jJ0Y2xhaW1fZ2VuZXJhdG9yX2luZm+jZG5hbWVvQW50aHJvcGljIEZpbGVzZ3ZlcnNpb25lMS4wLjBrc3BlY1ZlcnNpb25lMi40LjAAABA4anVtYgAAAChqdW1kYzJjcwARABCAAACqADibcQNjMnBhLnNpZ25hdHVyZQAAABAIY2JvctKEWQISogEmGCFZAgowggIGMIIBjaADAgECAhRA5aAK7sI50L64g/oGQgU9Z1UTADAKBggqhkjOPQQDAzBJMRcwFQYDVQQKEw5BbnRocm9waWMsIFBCQzEuMCwGA1UEAxMlQW50aHJvcGljIENvbnRlbnQgQ3JlZGVudGlhbHMgUm9vdCBDQTAeFw0yNjA4MDcxODQzNTZaFw0yODA4MDYxOTQzNTZaMEQxFzAVBgNVBAoTDkFudGhyb3BpYywgUEJDMSkwJwYDVQQDEyBBbnRocm9waWMgQ2xhdWRlIENvbnRlbnQgU2lnbmluZzBZMBMGByqGSM49AgEGCCqGSM49AwEHA0IABJh6CmvLUBgFFNU0vUKlOVtE6djd17L5SuwX0LemFisBM3dkd/3cyjxFA3Qo5S46fX0/ihY0VZ7mfb9KF703t5OjWDBWMA4GA1UdDwEB/wQEAwIHgDAVBgNVHSUEDjAMBgorBgEEAYPoXgIBMAwGA1UdEwEB/wQCMAAwHwYDVR0jBBgwFoAUzlHiBIFOZFsj+OPEz5o+nMHXXMIwCgYIKoZIzj0EAwMDZwAwZAIwMXMdFJ4BetLLVY7ORuE9noqbbAZOZn/aArXyTwFAZfKrPzxF2vPoJNf1+UCdg1XGAjBwX1zd9WGqYkqmL5SFqw1QySjr1zJfpJM9+1rdDwSPLMOPOjKuiXjoU/pUUeG9RwmhY3BhZFkNngAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAAPZYQBoyecUB4fLMKu/x0fEWyoG8CQ6fYeoQQRvWsa2kgILUV3hBShrj9jvR5grM0qC1/uZ/Ir1l58aOuXN381UumGc= CREDIT SIMULATOR AMOUNT $180,000 TERM 681218 MONTHLY $24,310 ANNUAL RATE 18.4% FIXED FOR THE WHOLE TERM AMORTIZATION

02 · Challenge

Can a simulator be as easy to read as a calculator?

People kept asking for a simulator because they had to run the numbers over and over to clear up doubts in the loan offer and origination process. That made the final decision feel complex and heavy.

That is what the interviews kept surfacing — "I don't know at what point in the process to flag if it's right for a type of product, because calculating the variables makes my decision harder." The complaint sounded like math, but it was really about not trusting the number in front of them.

The call I made

The request that came in was "build us a simulator". I decided not to take it as the problem statement. Across fifteen interviews the same thing kept surfacing: people were not missing a calculator, they could not tell which variable to move to fit the loan to their needs.

So I reframed the brief from "show the math" to "show the consequence of each adjustment" — and that reframe is what set the architecture of every screen that followed.

03 · Process

From the 5 Whys to two low-fi screens in six weeks.

It all started with conversations — fifteen interviews with current and prospective small-business owners, using the 5 Whys technique to get past the surface complaint and understand the real motivations.

Where the request died — and what the simulator changed.

Landing page Simulator prototype
Reaches the credit pageStep 01
15of 15
15of 15
Understands the offer shownStep 02
6
14
Trusts the figure as realStep 03
3
12
Can tell what to adjustStep 04
2
13
Would complete the applicationStep 05
4
11

What the comparison showed. 15 interviewees actively looking for credit walked the same five steps twice: once on the bank's live landing page, once on a simulator prototype with a dummy amortisation rate. On the landing, the drop happened at step 02–03: the information did not read as trustworthy, only as an approximation. Concrete figures — payment capacity, instalments, rate — gave certainty in a way that an estimate never did. The rate being dummy data did not matter: what changed was having a number tied to their situation instead of a range.

"On the page it's an approximate that doesn't feel real to me. I don't know if that's my payment or an example."

Interviewee 04 · landing page

"Here I can see what I'd be paying and how much room I have. That's what tells me whether I can take it."

Interviewee 09 · simulator prototype
The call I made

I decided the flow had to break into four phases — simulate, compare, request, confirm — because the interviews showed drop-off clustered wherever a screen asked for a decision and a data entry at the same time.

The rule I set: one screen, one decision. Anything that could not be reduced to a single question was split, even when that meant adding a step to the flow.

  1. Discovery & interviews

    15 small-business owners and 10+ insights mapped onto a single affinity board.

  2. Information architecture

    I rebuilt the flow into four clear phases: simulate, compare, request, and confirm. Each one with a single primary action.

  3. Wireframes & prototype

    4 low-fi screens and many rounds of usability testing with real users.

  4. Visual design & design system

    Component library connected to design tokens for the developer hand-off.

  5. Hand-off & QA

    Reviews with engineering and QA rounds before going to production.

04 · Solution

Every screen answers a question the user is actually asking.

Instead of forms, conversations. Instead of dense tables, summaries that are easy to scan. Each step has one job — and tells you exactly what comes next.

01Offer rejected
12:30▲ ▮ ▰
←Generate offerSTEP 3/3
Progress100%
Data capture
Offer
✕ NOT APPROVABLE

Approval will not be possible: the payment exceeds the client's maximum capacity.

Recalculate offer values →
LOAN AMOUNT−
Amount
$200,000
Insurance
$680
Annual rate
35%
Risk level
Excellent
PAYMENT INSTALMENTS−
First payment
$13,000
Second payment
$13,500
Maximum payment
capacity
$10,000
Calculate the offer
02Simulator · clean fields
12:30▲ ▮ ▰
←Offer recalculation
Last updated · 14/May/2023 · 3:40 pm
Gabriela Álvarez Mercado
Individual credit · ID 00000
Current offer values
Requested amount
$50,000
Term
8 months
Insurance amount
$800
Payment capacity
$10,000
Simulator
New term required
12 months
6 MONTHS48 MONTHS
Amount
$0.00

Amounts in multiples of $500

Recalculate credit
Clear recalculation
iWhen you adjust the conditions we take you to the terms and benefits section.
Adjust conditions
03Capacity exceeded
12:30▲ ▮ ▰
←Offer recalculation
Last updated · 14/May/2023 · 3:40 pm
Gabriela Álvarez Mercado
Individual credit · ID 00000
Current offer values
Requested amount
$50,000
Term
8 months
Payment capacity
$10,000
Simulator
New term required
12 months
6 MONTHS48 MONTHS
Amount
$50,000

Amounts in multiples of $500

Capacity exceeded$9,200

The second instalment nearly touches your $10,000 ceiling. Raise the term to 14 months to bring it down.

Recalculate credit
Clear recalculation
Adjust conditions
04Invalid range · risk
12:30▲ ▮ ▰
←Offer recalculation
✕ RISK-LEVEL CEILING

The prospect's risk level caps the maximum amount at $200,000.

Last updated · 14/May/2023 · 3:40 pm
Gabriela Álvarez Mercado
Individual credit · ID 00000
Current offer values
Requested amount
$50,000
Payment capacity
$10,000
Simulator
New term required
12 months
6 MONTHS48 MONTHS
Amount
$200,500✕

Valid range: $30,000 — $200,000

Recalculate credit
Clear recalculation
Adjust conditions
05Breakdown · ready to adjust
12:30▲ ▮ ▰
←Offer recalculation
Gabriela Álvarez Mercado
Individual credit · ID 00000
Simulated
New term
12 months
Amount
$50,000
CREDIT RECALCULATION
Insurance
$140
First instalment
$8,500
Second instalment
$9,600
Payment per thousand
$450
Annual rate
35%
Total amount
$56,600
✓It fits within the $10,000 payment capacity with $400 to spare.
Clear recalculation
Adjust conditions →

Simulated conditions are not saved until confirmed.

Swipe to see the five screens

Decision · 01

One screen, one interaction

Each number answers the user's need to know which banking factors to adjust — to set a more realistic amount with a lower long-term debt ratio.

Decision · 02

Information at a glance

By keeping the loan data pinned at the top, the decision to use the component to simulate better conditions feels reassuring and clear.

Decision · 03

Words that sound like the user

Interactions, keywords, and scannable features were written in language close to the user — which builds more trust in the process and the next steps.

What we gave up to get there.

What we deferred

Showing the simulator at the very start of an application

What users asked for was to see the simulator before being offered a credit. But because of the data drop-off, we first needed bureau data, monthly sales and business details — the minimum required to show a figure that means anything.
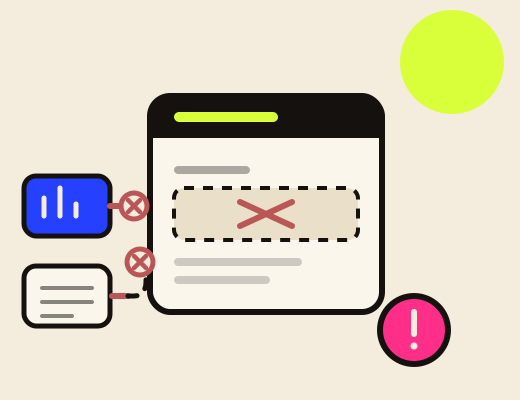
A simulator card with no figure to show, its data sources disconnected
Without real data there is no figure to show.
The call I made

The hardest disagreements were not about design — they were about implementation, with the enabling teams: Cloud, Database and Offer Service, the service that adjusts amortization rates from the risk and bureau evaluation.

Their position was fair: a simulator that renders without the factory offer data can show adjusted amounts that are inconsistent, or simply hang when the service does not answer. I did not push the simulator through as a pure front-end feature.

What I decided instead: no state of the simulator would ship without a defined behaviour for missing or late data. That turned an argument into a shared contract — loading, timeout, out-of-range and capacity-exceeded became designed states, and the release stopped depending on the service always being up.

05 · Outcome

Better time, better results.

What I'd do differently next time

Curious about my work?

Let's chat. I'm always open to understanding a project better, no matter how challenging or complex it seems.

Let's talk →